
KEY TAKEAWAYS:
-
-
A childhood in Nairobi and an article about Wall Street bonuses sparked Anuj Gupta's interest and decades-long path into commercial real estate finance
-
People before profit, a lesson he learned from his father, drives his leadership style
-
A decade in GE's operating cadence gave Anuj the strategic and operational skills to build businesses, and one rule he still applies today: three strikes on loan red flags.
-
He built a multi-billion-dollar originator but feels his most significant learning was seeing how a multi-product and multi-dimensional businesses can weather economic cycles and uncertainty. This is the principle behind Scythian Capital Management.
-
Anuj met co-founder Tim Geraghty when Tim was his banker at Deutsche Bank, financing deals at Waterfall, and the two shared the same convictions about credit, culture, and leadership
-
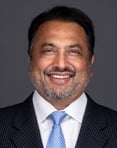 Despite growing up 7,500 miles from Wall Street, Scythian Capital Management Co-Founder and Managing Partner Anuj Gupta set his sights on a career in finance early on. He developed a strong affinity for the origination side of the business, joining a start-up originator early in his career then developing several origination platforms from the ground up, and eventually scaling one real estate originator from $150 million to $5 billion annually in commercial real estate loans that became a public REIT. That experience became the foundation for Scythian Capital Management, which he co-founded with Tim Geraghty.
We sat down with Anuj to learn more about that path.
What were some early lessons you learned about business?
I grew up in Nairobi, Kenya, and remember reading an article that claimed one Wall Street bonus could match a lifetime of earnings in Africa. I was only a teenager but that made a lasting impression on me and sparked my dream of one day working on Wall Street.
How I went about pursuing that dream came from my father. He was orphaned young and built several businesses from nothing: a bakery, a salt mining company and eventually real estate. When a dispute over real estate threatened to split the family, he walked away from his own share rather than risk losing relationships, because keeping the family and its reputation intact was far more important than anything else. People and reputation before profit was his philosophy, and it’s the principle that’s guided me throughout my career.
You’ve clearly come a long way since then. Tell us a bit about that journey.
My dream of working in finance took me first to the University of Michigan for my undergraduate degree where I convinced my father to let me buy a rental property to help pay for my expenses, sparking my interest in real estate. After graduating, I went to Boston University to earn my master’s degree. On one fateful day in Boston, I went to a job fair as a favor to a friend to distribute his resume. I wasn’t really expecting much, but I ended up meeting recruiters from NatWest Markets who asked to interview me on the spot. A few months later, I had an offer from a firm with a Wall Street address.
I worked for a few years as an analyst on the Mortgage & Asset Backed Securities teams at NatWest and then Greenwich Capital, which was acquired by NatWest.
Only three years after graduating, I joined some senior professionals who left Greenwich Capital to form their own firm. I joined the startup as a junior partner asked to lead the firm’s business development effort. We grew to more than 75 employees and over $1 billion in volume in just four years. I didn’t have a deep background I could draw on, so every day on the job was sort of scattershot and dependent on instincts. Just fire in every direction and follow up where we saw promise.
It worked but wasn’t elegant. Eventually, I decided I needed more experience and structure.
Is that what took you to GE Capital?
Exactly. And wow, what a difference! At GE I was tasked with building off-balance-sheet loan origination programs as a lever for future earnings growth. One program I conceptualized and launched was in the lower to middle-market real estate debt space and it grew to over a billion dollars in annual volume. I also built capital markets infrastructure that executed over $10 billion in transactions and co-led a $5 billion public-private joint venture that included the U.S. Department of Treasury during the Great Financial Crisis. I went from millions to billions.
GE’s leadership was laser focused on two things: credit discipline and strategic leadership. They were non-negotiables.
On the credit side, I worked alongside people who were relentlessly disciplined. One senior executive on the real estate side followed a very strict standard: one nick on a deal, he’d hear you out. Second nick, he wanted a letter of explanation. Third nick, walk away. The lesson was to develop a strong framework to size up loans and very quickly identify anomalies in the story and motivations for the loan. At GE, this sort of discipline was built in on the front end to screen billions of dollars of loans before they even made it to more detailed analytics and underwriting. I continue to evaluate every deal that crosses my desk the same way today.
And the leadership side?
The amount of strategic training at GE Capital was intense and goes back to Jack Welch who grew GE from $14 billion in market capitalization to over $400 billion. The company was intensely strategic, requiring every business leader to build three plans annually: Session C, which was people and talent; Session I, which was long-range strategy; and Session II, which covered operational budgeting and resource allocation. We presented these plans to a senior leadership committee during business reviews. This forced us to constantly look ahead, know our market, and understand how the various competitive and economic forces and challenges would alter with time. We were constantly building the future state of our businesses.
Part of that training happened at Crotonville, GE's vaunted training ground. Business leaders would go for a week, sometimes two, in addition to numerous one-off training sessions. There, we'd listen to deans from all the Ivy League schools, guest CEOs, and hear GE's top executives, including the CEO, discuss strategy, experience, lessons learned, infrastructure, people, and how to bring it all together in our businesses. There was always this idea at GE that if we weren’t the top three in our space, we needed to figure out how to get there. The most effective part of the training was understanding how to build big-company infrastructure.
Roughly 50% of our time was spent focused on people and planning for the future, and 50% on achieving near term business goals; I recall one GE executive saying that by June he was already onto the next year. It is an entirely different way of thinking and leading.
Then Waterfall brought you in. What were the lessons there?
Waterfall recruited me to help build originations and capital markets expertise. They were well aware of the originations programs I had built at GE and had purchased some of the offerings from those transactions. Interestingly, one of the first things I did after joining Waterfall was acquire GE’s portfolio of middle-market real estate loans, the largest trade the firm had ever done at the time. From there, I took an underperforming small business originator the firm was trying to create and re-launched it as a commercial real estate originator that I led. The originator grew exponentially from there into multiple products, all launched from the ground up and eventually becoming a public REIT with over 200 people. Real estate debt originations volume went from $150 million to over $5 billion annually. I eventually oversaw $16 billion in originations and over $5 billion in acquisitions of businesses and loan portfolios prior to my prescient choice to exit due to misalignment on strategy.
It was through this process that I understood the power of a diversified multi-product and multi-dimensional business and where the labels capital-heavy and capital-light come from: capital-heavy loan originations and acquisitions coupled with capital-light fee generating government license related businesses. COVID proved the model whereby the capital-light SBA business went on to do over 100,000 Paycheck Protection Program loans and the Freddie Mac Small Loan Business continued to fund loans. This business model is different and unique. Many investors we present to are confused by it but it is an incredibly robust business model that spans a large opportunity set for investors and ensures a business can survive through economic cycles and shocks and optimize returns.
How did you meet Scythian Co-Founder Tim Geraghty?
Tim was the Deutsche Bank banker financing the business I was running at Waterfall. He had unique perspective as he was in a position of advising investment managers, funds and specialty finance platforms in financing and securitization transactions. He joined Waterfall soon after to help build the firm’s global capital markets infrastructure while we partnered on growing the loan originations and acquisitions business. Tim and I saw the same opportunity: lower and middle-market commercial real estate credit is large, structurally underserved, and hard to replicate at scale. Too fragmented for regional banks, too small for mega-managers. Competing there takes Main Street relationships and a Wall Street toolkit, and few firms have both. Tim and I did. We also shared the same philosophies about credit, about culture, and about the kind of firm we wanted to lead. We decided that building it ourselves was the next logical step.
How did you translate that opportunity into Scythian?
We built Scythian around a simple idea: single-strategy credit works until it doesn’t. Too many times firms with a singular focus have to keep their workforce going given the overhead costs no matter what the environment. That leads to the all too familiar boom-and-bust cycle.
We pair a capital-heavy business focused across two dimensions, bridge lending and loan acquisitions, with capital-light government-licensed businesses, like small agency, SBA, HUD, USDA, and tax-exempt financing. That mix gives us the flexibility to lean in whichever direction the market’s going. When credit tightens, the capital-heavy side can shift into opportunistic acquisitions and the capital-light fee side keeps cash flowing, and can even grow. We strongly believe that an important part of running a business is also knowing when not to run it.
We didn’t want to just build an asset management firm. We want to build a mini-GE Capital: a diversified business with broad infrastructure focused on a space we know well. A firm established to invest with discipline across economic and real estate cycles, preserving downside protection in strong markets while maintaining the flexibility to capitalize on dislocation. Our cradle-to-grave lending model aligns origination with long-term performance by keeping underwriting, closing, servicing, and asset management under one roof.
You mentioned culture as part of what you and Tim aligned on. How does that show up day to day?
Time and again we have seen very successful people assume they can apply their skill set to any situation, but some businesses require decades of experience from which instincts and vision are honed. Tim and I have that experience and foresight but also have no doubts about surrounding ourselves with and trusting the right people, talent who will go anywhere and do anything to make sure the right things are done. Every platform I’ve helped build, from that scattershot startup to the GE program to what we grew at Waterfall, came down to who was in the room and whether they trusted each other enough to do hard things together. I’ve felt and experienced that people always have an extra gear to pull but need to be in the right environment and treated properly to pull it. That's what a high-performance culture does: it creates the conditions for people to perform at their best.
We have an entire watch list of people today that we would hire immediately if they would join. These are people we know and have either done transactions alongside or even built businesses with and see us as fair and just leaders. They are strong cultural contributors and experienced performers. Tim and I feel with our targeted staffing we will be well-established at inception with over a century or more of collective experience.
What does success look like for Scythian 10 years out?
GE used to have catchy motivational slogans. Ours is 10 by 10. If we do this right, I see us as a $10 billion+ asset manager in 10 years, which I think is very much within reach with the right people around us. Our greater focus, though, is to build an enduring institution of real scale. One grounded in real value creation and designed to make a meaningful impact for decades. Allocators are trusting us with capital for years at a time, and that trust is worth more when the same people who underwrote a deal are still here to see it through a full cycle.
Long term, I hope to build something closer to a family than a firm, with partners and employees who are invested and still here in 10 or 20 years, sharing meaningfully in what we build together. There is no better feeling than being part of a close-knit team that lives through the trials and tribulations of a new business and celebrates its accomplishments.